
Accepting card payments is an essential part of running a modern business. Whether a company operates a retail shop, restaurant, online store or professional service, customers expect convenient and reliable ways to pay. Payment 247 helps businesses explore payment solutions that suit their operational requirements and customer needs. Choosing the right Merchant Credit Card Processing solution can simplify transactions, support secure payments and improve the overall purchasing experience.
What Is Merchant Credit Card Processing?
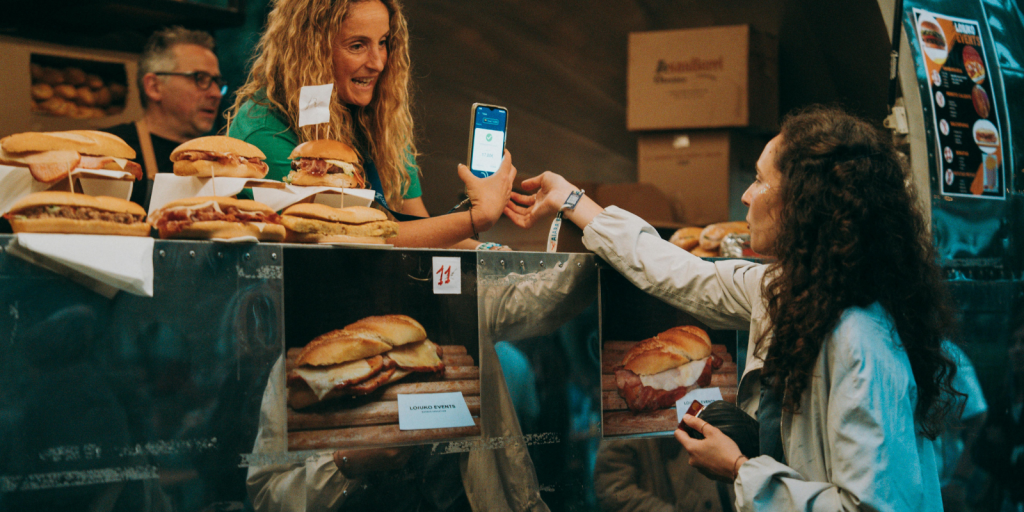
Merchant credit card processing is the service that enables businesses to accept credit card payments from customers. It connects the merchant’s payment terminal or online checkout with the financial institutions and card networks responsible for authorising and processing transactions.
Payment 247 can help businesses understand the payment options available for different selling environments, including face-to-face transactions and online purchases. Depending on the provider and service arrangement, a solution may include payment terminals, online gateways, transaction reporting and other tools that support everyday operations.
For businesses, an effective payment setup is more than a way to collect money. It can help reduce checkout friction, simplify payment administration and provide customers with a familiar way to complete purchases.
How Merchant Credit Card Processing Works
Although a card payment may take only a few seconds, several steps take place behind the scenes to complete the transaction.
- Payment initiation: The customer presents a card to a terminal or enters card details through an online checkout.
- Secure transmission: The payment information is transmitted through the relevant payment system.
- Authorisation request: The payment processor routes the request through the appropriate card network to the card issuer.
- Verification: The issuer checks the transaction and determines whether it should be approved.
- Transaction response: The approval or decline is communicated to the merchant’s payment system.
- Settlement: Approved transactions are processed for settlement, with funds transferred according to the provider’s arrangements.
Authorisation and settlement are separate stages. An approved transaction does not necessarily mean the money has already arrived in the business’s bank account.
Understanding this process can help merchants evaluate payment providers and establish realistic expectations about transaction handling and settlement times.
Benefits for Modern Businesses
A suitable card payment system can improve several aspects of business operations.
Greater Customer Convenience
Customers increasingly expect to pay by credit or debit card, contactless payment or supported digital wallet. Offering familiar payment methods allows customers to choose how they pay and can make checkout more straightforward.
Faster Checkout Experiences
Modern payment terminals and integrated checkout systems can process transactions quickly. This is especially useful for busy retail environments, restaurants and businesses that handle a high volume of customer payments.
More Sales Opportunities
Accepting cards allows businesses to serve customers who prefer cashless payments. Online payment processing also makes it possible to sell products and services beyond a physical shop or local area.
Simplified Financial Records
Many payment platforms provide transaction histories, downloadable reports and reconciliation tools. These features can help business owners monitor sales, review refunds and compare transaction records with accounting information.
Support for Business Growth
As a business expands, its payment needs may become more complex. A flexible payment solution may support additional terminals, online sales, recurring payments or multiple business locations, depending on the provider’s available services.
Essential Security Features
Payment security should be a priority for every business that accepts card transactions. A suitable system should protect sensitive information and help reduce the risk of fraudulent activity.
Important security considerations include:
- PCI DSS compliance: Businesses must understand and meet the applicable Payment Card Industry Data Security Standard requirements.
- Encryption: Appropriate security measures help protect payment information during transmission.
- Tokenisation: Where supported, tokenisation replaces sensitive card details with substitute values for certain payment operations.
- Fraud detection: Available monitoring tools can help identify suspicious transaction patterns.
- Secure account access: Strong passwords and multifactor authentication can help protect payment dashboards.
- Staff awareness: Employees should understand safe payment handling and procedures for reporting suspicious activity.
Businesses should also avoid retaining sensitive card data unnecessarily and should never store card security codes after authorisation. The precise requirements depend on the payment environment and how the business handles cardholder information.
Choosing Between In-Store and Online Payments
The right payment system depends on how a business sells its products or services.
In-Store Card Payments
Retailers, cafés, restaurants and other customer-facing businesses may benefit from physical payment terminals. Depending on the equipment, these can support chip-and-PIN, contactless cards and compatible digital wallets.
Integrated point-of-sale systems can also connect payments with sales records, helping staff manage transactions and reduce manual administration.
Online Card Payments
E-commerce businesses typically use a payment gateway or an integrated checkout solution. Customers enter their payment details through a secure payment page, and the transaction is submitted for authorisation.
Businesses should consider mobile compatibility, checkout simplicity, fraud prevention features and integration with their website or online store.
Omnichannel Payments
Companies that sell both online and in person may benefit from systems that provide consolidated transaction reporting. Depending on the provider, additional features may help connect sales records across channels and make financial reconciliation easier.
Understanding Processing Fees and Costs
Payment processing costs can influence a business’s profitability, making it important to understand the complete pricing structure before choosing a provider.
Common charges may include:
- Transaction fees
- Monthly service charges
- Payment terminal rental or purchase costs
- Payment gateway fees
- Chargeback or additional service fees
Some providers charge a percentage of each transaction, while others combine percentage-based fees with fixed charges. Pricing may also vary according to card type, transaction method and business risk profile.
When comparing Merchant Credit Card Processing providers, businesses should consider their average transaction value, monthly card turnover and expected transaction volume. A provider with a low advertised rate may not necessarily offer the lowest overall cost once additional charges are included.
Merchants should also review contract terms, cancellation conditions, settlement schedules and customer support arrangements before committing.
How to Select the Right Merchant Payment Provider
Choosing a payment provider involves balancing cost, security, reliability and functionality.
Before making a decision, businesses should consider these questions:
- Does the service support the payment methods customers prefer?
- Can it handle the business’s online and in-person transactions?
- Are all fees and contractual obligations clearly explained?
- Does it offer appropriate security and fraud prevention tools?
- Can it integrate with existing accounting or point-of-sale software?
- Are settlement times suitable for cash-flow requirements?
- Is support available when payment problems arise?
Evaluating these factors helps businesses select a solution that meets their current requirements while allowing room for future growth.
Frequently Asked Questions
What is a merchant account?
A merchant account is a payment arrangement that enables a business to accept card transactions. Depending on the provider, businesses may instead use an integrated payment service that combines processing and fund management.
Is merchant credit card processing suitable for small businesses?
Yes. Small businesses can use card processing to offer convenient payment options, improve transaction records and serve customers who prefer cashless payments. The most suitable service depends on transaction volume and budget.
How long does card payment settlement take?
Settlement times depend on the provider, transaction arrangements, banking processes and account terms. Businesses should confirm the expected schedule before selecting a service.
Are processing fees the same for every business?
No. Fees can vary according to the provider, transaction volume, card type, payment method and additional services included in the agreement.
Conclusion
An effective payment system helps businesses accept customer payments conveniently while supporting security, accurate transaction records and smoother daily operations. From physical payment terminals to online checkout solutions, the best approach depends on a company’s sales channels, budget and future plans. By comparing costs, security features and service arrangements, businesses can choose Merchant Credit Card Processing that supports customer satisfaction and sustainable growth.
Contact
Phone: +44 20 3556 1274
Email: [email protected]
Address: 59–60, Gainsborough House, Thames St, Windsor, SL4 1TX.